BlockDesk Best of the Week: Government Bitcoin Moves, AI’s Transparency Crisis, Oil Shock Markets, and Yu-Gi-Oh’s Rarity Gambit
A week defined by state-level crypto maneuvers, artificial intelligence’s mounting accountability crisis, an oil-driven market shock, and a trading card announcement that sent collectors into a frenzy — October 5–9, 2026 delivered the kind of cross-sector turbulence that separates informed capital from reactive noise. BlockDesk breaks down everything that mattered.
Crypto
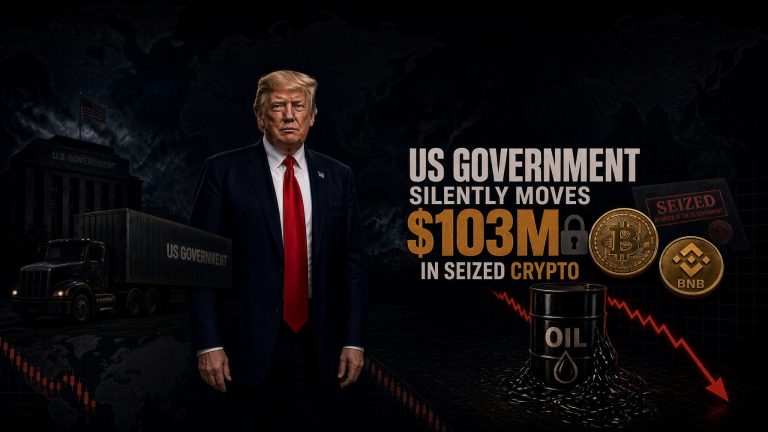
The most consequential on-chain event of the week arrived without a press release. The U.S. government executed a silent transfer of approximately $103 million in seized digital assets — a combination of Bitcoin and BNB — moving funds through wallet addresses that blockchain analytics firms flagged within hours of the transactions settling. No official statement accompanied the movement, leaving market participants to speculate on timing, destination, and intent.
Government wallet activity of this magnitude historically generates one of two reactions: a short-term sell-side overhang as traders pre-position against anticipated auction liquidation, or a neutral shrug if funds are being transferred between custodial addresses as part of routine administrative housekeeping. This week, sentiment leaned cautious. Bitcoin absorbed the news without a dramatic leg down, but derivatives markets showed elevated put activity in the 48-hour window following the transfer’s public identification — a signal that professional desks were hedging against a potential dump scenario rather than dismissing the risk outright.
What makes this transfer structurally significant is its composition. The inclusion of BNB alongside Bitcoin is unusual for U.S. government custody operations, which have historically concentrated holdings in Bitcoin. The BNB component suggests these assets likely originated from enforcement actions targeting exchanges or decentralized finance protocols with Binance Smart Chain exposure — a detail that narrows the probable case origin considerably and hints at the ongoing breadth of federal digital asset enforcement activity.
The U.S. government’s $103M silent transfer of seized Bitcoin and BNB is the single most market-relevant event of the week. Unannounced sovereign-scale crypto movements inject structural uncertainty into price discovery and underscore that the largest unpredictable seller in digital asset markets remains an arm of the federal government — not a hedge fund, not a whale, not a protocol treasury.
Government-held Bitcoin reserves across active enforcement cases represent a persistent, non-market-driven supply overhang. With no statutory obligation to notify markets ahead of transfers or liquidations, any position built on near-term BTC price stability must account for the possibility of sudden government-initiated sell pressure at zero warning.
AI & Technology
The artificial intelligence industry’s transparency problem reached a new inflection point this week as the gap between chip deployment rhetoric and verifiable on-the-ground reality widened into territory that serious investors can no longer ignore. Three distinct fault lines dominated coverage: the accelerating push for AI content watermarking standards, the emergence of a dedicated personal AI hardware category, and a growing body of evidence that the pace of AI chip deployment is materially lagging the capital expenditure narratives being sold to Wall Street.
On watermarking, regulatory pressure is crystallizing into something with teeth. Policymakers across multiple jurisdictions are moving toward mandatory provenance labeling for AI-generated content, a development that creates both compliance cost burdens for large model operators and, paradoxically, a new moat for platforms that embed watermarking infrastructure early. The technical standards debate is far from settled — cryptographic watermarking, metadata embedding, and behavioral fingerprinting each have advocates — but the direction of travel is unambiguous. AI-generated content will be labeled, and the companies that own the labeling infrastructure will extract rent from that position.
Personal AI hardware represents the week’s most forward-looking technology story. A new generation of edge devices — purpose-built to run large language model inference locally, without cloud dependency — moved from prototype announcements toward concrete product timelines. The privacy case is straightforward: sensitive queries processed on-device never touch a server. The performance case is more nuanced, with current personal AI silicon still lagging cloud-scale inference for complex multi-step reasoning tasks. But the trajectory is clear, and the category is attracting serious capital.
The chip deployment gap story is the one with the most immediate financial consequences. Multiple enterprise buyers have reported significant delays between GPU order placement and actual rack-level deployment, with supply chain bottlenecks, power infrastructure constraints, and cooling system lead times all contributing to a situation where announced AI capex is not translating into operational compute capacity on the timelines that earnings models assume. For investors pricing AI infrastructure stocks on forward utilization rates, this gap represents material downside risk to near-term revenue projections.
AI infrastructure stocks priced on aggressive deployment timelines face a reckoning as chip-to-rack lag times extend well beyond initial estimates. Capital expenditure announcements are not the same as operational capacity — and the spread between the two is widening heading into Q4 2026 earnings season.
Global Markets
U.S. equities spent the week navigating a collision between macro pressure and the opening salvos of earnings season, with an oil shock providing the most acute single-session volatility of the period. Energy prices spiked on supply disruption signals, triggering a broad risk-off rotation that hit growth and technology names hardest while briefly lifting energy sector proxies — a familiar playbook that nonetheless caught momentum-heavy portfolios on the wrong side of the tape.
The macro backdrop remains structurally unresolved. Credit markets are pricing in a higher-for-longer rate environment that equity multiples have not fully digested, and the earnings reality beginning to emerge from early reporters is one of margin compression rather than the revenue acceleration that consensus estimates had baked in. Consumer-facing companies in particular are flagging demand softness that contradicts the resilient spending narratives that buoyed index levels through much of 2026’s first three quarters.
Across the Atlantic, Britain’s political landscape generated its own form of market-relevant uncertainty. The Conservative opposition’s hard-right realignment under current leadership is introducing a new variable into UK fiscal credibility calculations, with bond markets watching closely for any signals that a future government would pursue aggressive supply-side fiscal experiments reminiscent of the gilt market disruption of 2022. The pound held its ground this week, but the political risk premium embedded in UK assets is not zero — and it is trending in the wrong direction for sterling bulls.
The oil shock dynamic deserves specific attention as a forward-looking signal. Brent crude’s sensitivity to Middle East supply disruption narratives remains acute, and any sustained move higher in energy prices feeds directly into inflation expectations, complicating the path for central banks that had been quietly signaling a more accommodative posture heading into year-end. A re-acceleration of inflation driven by energy would reset that calculus entirely, with consequences that ripple from rates through equities and into crypto risk appetite simultaneously.
The convergence of oil-driven inflation risk, margin compression in early earnings reports, and a higher-for-longer credit market is constructing a wall of worry for Q4 equities. Positioning that assumes a soft landing remains the base case is carrying more tail risk than current volatility surfaces suggest.
Trading Cards
Yu-Gi-Oh!’s OCG division dropped the week’s most anticipated collectibles announcement: the official confirmation of the “Rarity Collection: Climax Scene Edition,” an 80-card set scheduled for release on February 27, 2027. The set introduces Grand Master Rares — a new rarity tier positioned above existing premium finishes — alongside a lineup of Over Frame reprints that the secondary market has been demanding for years.
For the trading card investment community, the structural details matter as much as the card list itself. The introduction of a new rarity tier into an established franchise is a double-edged event. On one hand, Grand Master Rares create a fresh demand ceiling for the highest-grade copies, pulling collector and speculator attention toward the top of the rarity curve. On the other hand, Over Frame reprints directly suppress the secondary market value of existing copies of reprinted cards — a dynamic that rewards buyers of the new set while penalizing holders of the originals who failed to exit before the announcement.
The February 27, 2027 release date gives the market approximately four and a half months to price in the reprint impact. Historical OCG reprint set behavior suggests the sharpest value compression in affected cards occurs in the 30-day window following announcement, with a partial recovery as the actual print run size becomes clearer. Cards not confirmed for inclusion in the 80-card roster have already seen speculative buying from traders positioning for the reprints-not-included premium.
The Rarity Collection: Climax Scene Edition’s 80-card roster and Grand Master Rare tier represent the most significant structural addition to OCG rarity infrastructure in recent memory. Secondary market participants should treat the February 27, 2027 date as a hard deadline for reprint-exposure liquidation decisions — not a distant event to monitor casually.
Investor Takeaways
Government wallet movements of $103M+ remind markets that the largest non-commercial crypto seller operates without disclosure obligations. Any long position in BTC or BNB carries embedded sovereign liquidation risk that cannot be priced through conventional on-chain metrics alone.
The chip deployment gap between announced infrastructure spend and operational compute is widening. Investors pricing AI infrastructure names on forward utilization assumptions face material earnings risk as supply chain delays push actual deployment timelines deeper into 2027.
An oil shock intersecting with margin-compressed earnings and a higher-for-longer rate environment creates a compounding risk scenario for equities. Watch Brent crude as the leading indicator for whether the Q4 soft-landing narrative survives the next six weeks intact.
New rarity tiers in established TCG franchises are a proven demand-generation mechanism — but they simultaneously create reprint-driven value compression for existing premium card holders. The announcement-to-release window is where the arbitrage opportunity concentrates.
Opacity, Accountability, and Compression: The Week’s Dominant Theme Is Trust
Strip away the sector labels and a single thread runs through every major story this week: the tension between institutional opacity and market accountability. The U.S. government moved $103 million in digital assets without a word. AI companies are deploying chips slower than their capital expenditure narratives imply and generating content that regulators are demanding be labeled. Equity markets are being asked to trust earnings models that early reporters are quietly dismantling. Even the trading card market is grappling with the trust implications of new rarity tiers that can devalue existing holdings overnight.
In each case, the information asymmetry favors institutions over retail participants — and in each case, the window for informed positioning is narrow. The investors who moved first on the government wallet signal, who interrogated AI infrastructure utilization rates before consensus caught up, who sold reprint-exposed card positions within 48 hours of the OCG announcement — those are the participants who extracted value from this week rather than absorbing it as loss.
Heading into the coming week, watch three things: the destination and disposition timeline for the $103M government crypto transfer; early Q4 earnings from AI infrastructure-adjacent names that will either validate or puncture the deployment timeline narrative; and Brent crude’s trajectory as the primary stress variable for the higher-for-longer rate path. If energy stays elevated and early earnings disappoint, the soft-landing consensus breaks — and risk assets across every sector covered this week will reprice accordingly.
This article is for informational purposes only and does not constitute financial advice. Always conduct your own research before making investment decisions. BlockDesk News aggregates and analyzes publicly available information; nothing herein represents a solicitation to buy or sell any asset class referenced in this report.